Theodore's edition. Researched from primary sources — company filings, exchange announcements, central-bank statements and wire reporting — not from Jarvis's briefing. AI-generated — not investment advice.
Today in one minute
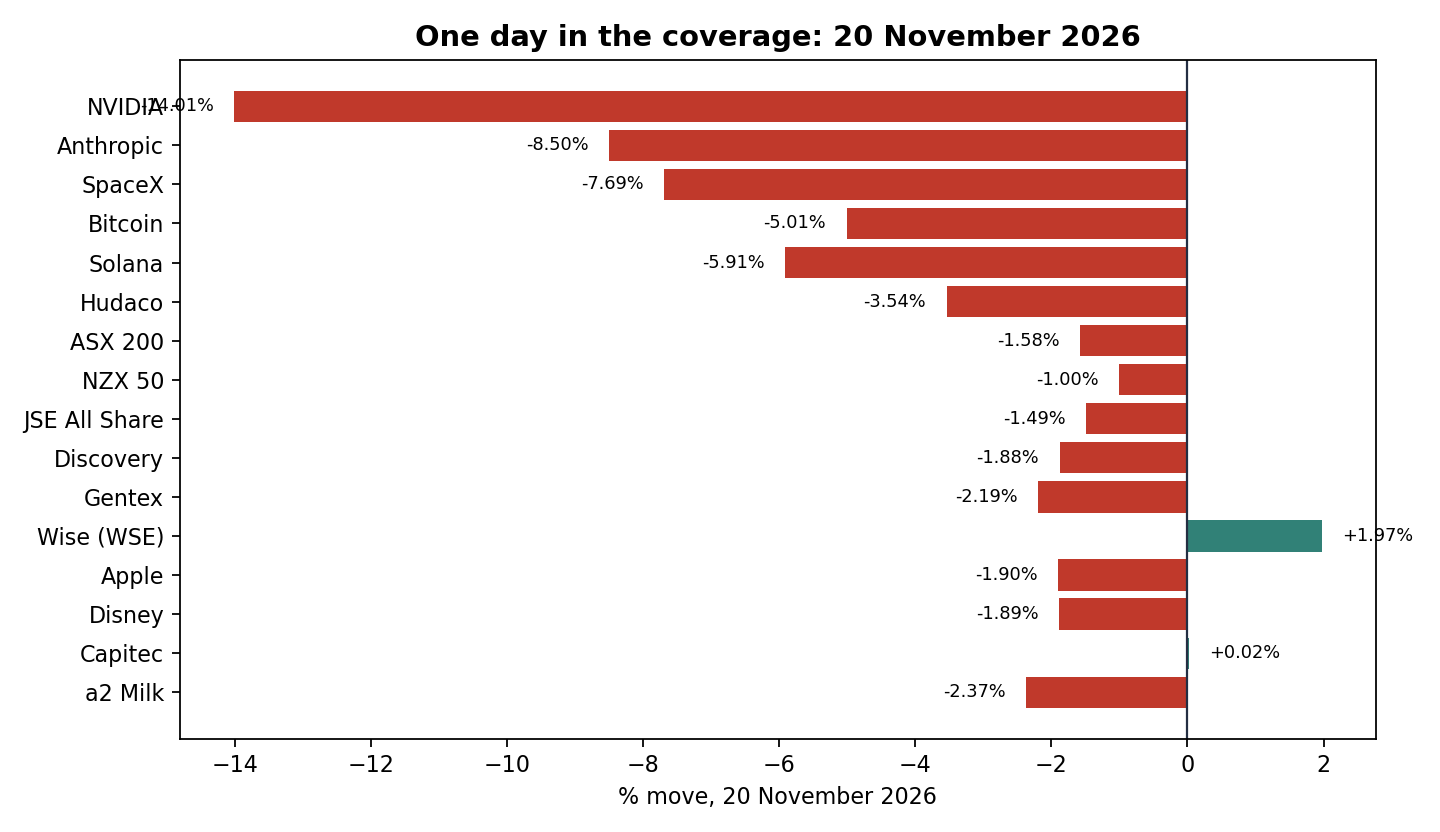
Wall Street's sell-off turned into a rout on Friday. The S&P 500 fell 3.70% to 6,910.39 — its seventh straight loss and now in correction — and the Nasdaq fell 5.28%. The sell-off was already under way before the day's NVIDIA news landed — by 13:01 ET the SPY ETF was already down 2.22% and the QQQ ETF down 3.87%. Reuters then reported (14:13 ET) that SEC enforcement staff are examining potential accounting issues at NVIDIA, and the stock fell 14.01% to US$125.53. The SEC declined to comment and there is no finding of wrongdoing.
Anthropic faded back towards its IPO price on day two. It closed at US$88.91, down 8.50%, with an intraday low of US$83.05 — barely above the US$83 offer price. SpaceX fell 7.69% to US$127.79, below its US$135 IPO price.
South Africa fell for an eighth day. The JSE All Share lost 1.49% to 104,638.77 and the rand closed around R17.47 to the dollar. Discovery's AGM passed every resolution; its shares fell 1.88% anyway. Hudaco, a Watchlist name, fell 3.54% to R177.00 on no news.
Bitcoin broke below US$60,000. It closed at US$58,799, down 5.01%. Final 19 November ETF figures showed US$582.3m out in one day — BlackRock's IBIT alone lost US$541.1m, its largest outflow since launch.
Australia and New Zealand followed the US down. The ASX 200 fell 1.58% in its seventh straight loss and its worst week since March 2020; the NZX 50 fell 1.0%.
NVIDIA and the SEC report: the sell-off finds a cause
Friday 20 November was the worst day of the correction so far.
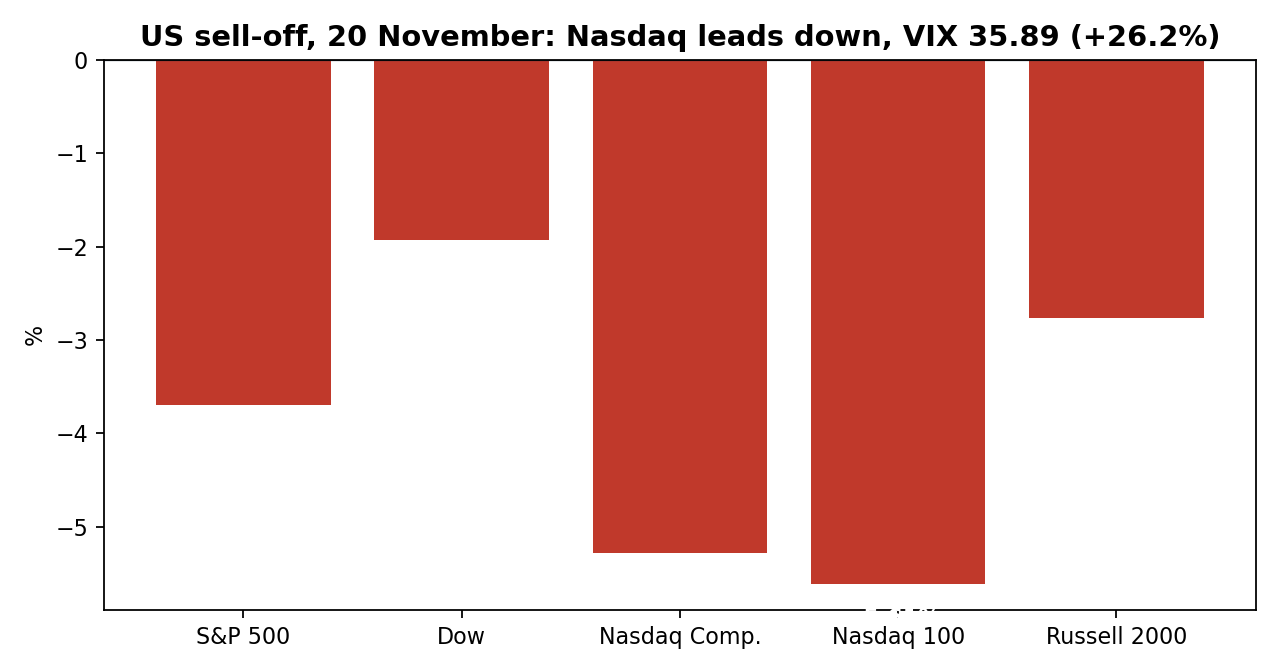
S&P 500: 6,910.39, −3.70% — seventh straight loss, the longest streak since February 2020; now in correction, more than 10% below its 6 October record. Technology fell 7.11%; consumer staples (+0.68%) was the only sector to rise.
Dow: 48,147.33, −1.93% — fifth straight loss.
Nasdaq Composite: 22,617.73, −5.28% — now negative for the year (−2.7% year to date, per AP/Reuters wraps). Nasdaq 100: 25,028.98, −5.61%.
Russell 2000: 2,581.79, −2.76%. VIX closed at 35.89, +26.20%, with an intraday high of 40.03. The 10-year Treasury yield fell about 12–14bp to ~4.92% — a flight to safety, not a rate story this time. Brent settled at US$92.57, +0.64%.
The report that deepened the fall, per Reuters on Friday (14:13 ET) citing two people briefed on the matter: SEC enforcement staff are examining potential accounting issues at NVIDIA. The timing matters: the wire landed in a sell-off already under way — at 13:01 ET, SPY was already down 2.22% and QQQ down 3.87% — so it is news that arrived during the fall, not evidence of what started it. Reuters could not determine when the inquiry began or which issues are in focus; the SEC declined to comment; NVIDIA has not been found to have done anything wrong. The Wall Street Journal had reported on 17 November that the SEC was probing whether disclosures misled investors. Separately — and confirmed by the Attorney General's own press release — California's Attorney General on Thursday served an investigative subpoena concerning whether advanced chips or confidential information reached China and whether NVIDIA or former CEO Jensen Huang misled investors (https://oag.ca.gov/news/press-releases/attorney-general-bonta-serves-investigative-subpoena-nvidia). The subpoena is confirmed; the SEC examination remains a reported inquiry, not a finding — no primary filing confirming its scope was retrieved in this run.
The shares did the rest: NVIDIA closed at US$125.53, down US$20.45 (−14.01%), its seventh straight loss in most wraps. The chip complex followed — the PHLX Semiconductor Index fell 10.7% (AP), Micron −13.89%, AMD about −13.3%, Broadcom about −12.1%. This lands on the vulnerabilities the last two briefings flagged from NVIDIA's own filing: US$81bn of receivables at 64 days, US$39.7bn of inventory, US$390bn of supply commitments and up to US$118bn of guarantees, a delayed 10-Q, a founder-CEO whose departure took effect on 11 November (announced 12 November, per NVIDIA's 8-K: https://www.sec.gov/Archives/edgar/data/1045810/000104581026000082/nvda-20261111.htm), and House transcribed interviews on 1–2 December. None of that proved anything about accounting. It is why an unconfirmed inquiry moved the stock 14% in a day: the market was already being asked to trust numbers it could not yet check in a filed 10-Q.
Analyst consensus — NVIDIA (NVDA): Moderate Buy. TipRanks (40 analysts, past 3 months): 26 Buy, 13 Hold, 1 Sell. Average target US$229.30 (TipRanks, as at the 20 Nov close), +82.7% vs US$125.53; range US$130–$345. Note the low target, Seaport Global's US$130, is now only 3.6% above the price. No 20 November-dated target change was found; the latest actions remain the post-results cuts (Jefferies US$300→$250, Goldman Sachs Buy US$220, Barclays US$210, Citi Buy US$225). TipRanks' average has drifted down from US$232.33 in yesterday's crawl — treat the exact level as moving. Sources: TipRanks; Reuters, 20 Nov 2026; AP market wrap, 20 Nov 2026.
Anthropic, day two: the IPO premium nearly gone — and SpaceX below issue
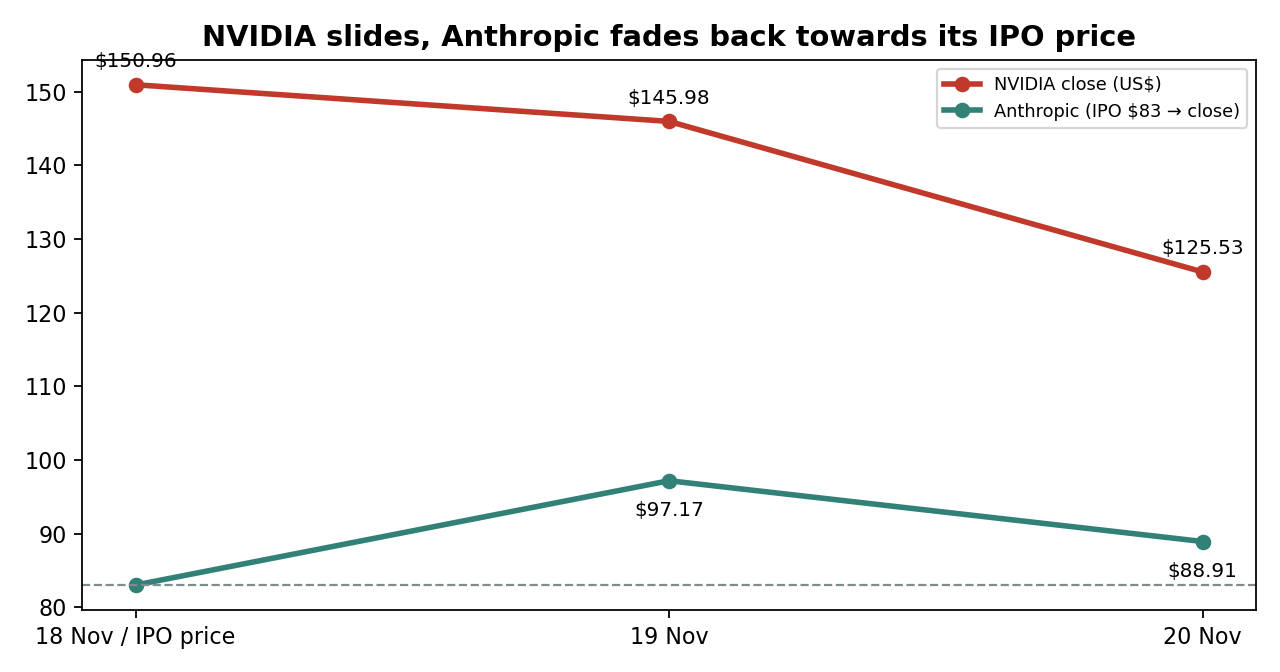
Anthropic closed its second session at US$88.91, down 8.50% (feed close; AP and Longbridge prints of US$88.30 / −9.1% differ slightly and could not be reconciled — the feed close is used here). The intraday low was US$83.05, five cents above the US$83 IPO price. Anthropic did announce on 20 November — the closing of its IPO: the underwriters exercised the full 147 million-share option, taking gross IPO proceeds to Anthropic to US$91.6bn excluding secondary shares, alongside the concurrent US$26bn private placement (https://www.anthropic.com/news/ipo-close). Those combined proceeds are gross, not net. The share price still faded: this was the debut premium meeting a sector rout. Two days in, the question from the pricing still stands — September-quarter revenue of US$16.96bn against US$9.86bn of compute and infrastructure cost (58 cents per dollar of revenue), and about US$900bn of purchase and lease commitments. At US$88.91 the market is no longer paying much for the answer in advance.
SpaceX told the same story from the other side of its listing: US$127.79, −7.69%, below its US$135 June IPO price. Reporting on Thursday's completed US$32bn bond sale (via an Apollo-managed vehicle, to buy NVIDIA Rubin GPUs and lease them to SpaceX) put the largest tranche's yield at 8.259%, against a 5.95% average for US investment-grade debt that day — second-hand Bloomberg/FT reporting, no primary SpaceX release retrieved. If those terms are right, the debt market is charging SpaceX's AI build-out like a credit risk, not like a launch monopoly.
Analyst consensus — Anthropic (ANT): still no formal consensus — underwriters remain in the quiet period. Early independent targets vs the US$88.91 close: Melius Buy US$155 (+74%), Needham Buy US$150 (+69%), Wolfe Outperform US$135 (+52%), Citizens Outperform US$125 (+41%), New Street Buy US$105 (+18%), Freedom Finance Buy US$101.90 (+15%), KGI Outperform US$100 (+12%). Morningstar's US$92 fair value is now only 3.5% above the price. SpaceX (SPCX): Buy, average target US$257.50, +101% vs US$127.79; range US$70–$800 — the range, not the average, remains the honest summary. Sources: as in the 19–20 Nov editions; prices Finnhub/StockAnalysis 20 Nov closes.
South Africa: eighth straight loss, Discovery's AGM passes, Hudaco slips
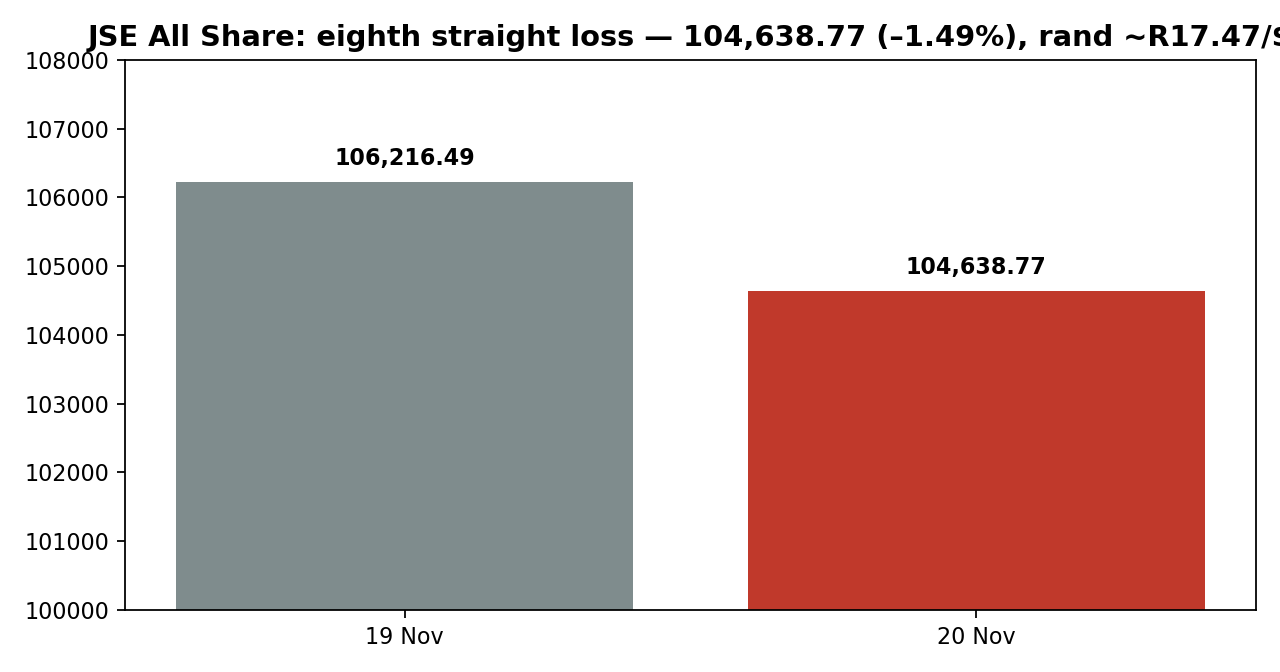
The FTSE/JSE All Share closed at 104,638.77, −1.49% (Top 40 −1.58%), extending an eight-session losing run that began a week before the CPI release: Stats SA published the 5.2% October CPI print on 18 November (https://www.statssa.gov.za/?PPN=P0141&SCH=74489&page_id=1854), and it added pressure over the final three sessions rather than starting the streak. The rand was near a one-year low early on Friday at R17.56 to the dollar (Reuters, 07:40 SAST), pressured by Johannesburg coalition talks and a stronger dollar, and closed around R17.47 on market feeds; the SARB's official reference rate was R17.44. Gold fell as low as US$3,515 an ounce on Friday in Bloomberg reporting carried locally, on track for an 8% weekly fall — which removes the cushion that supported the rand and the miners earlier this year. There was no new SARB release on Friday; the 19 November hold at 7.25% (4–3, three members wanting a hike) stands, with the next decision on 28 January 2027 and the next CPI on 15 December.
Discovery (DSY) closed at R259.30, −1.88%. Its AGM results were published on SENS on Friday morning (02:26, 20 Nov): the AGM was held on 19 November, all resolutions were duly approved, with 80.65% of shares present or by proxy. The remuneration policy passed 96.28% / 3.72% and the remuneration report 97.19% / 2.81% — no protest vote. KPMG and Deloitte were re-appointed as joint auditors at 99.99%. Faith Khanyile's retirement took effect at the conclusion of the AGM; it was pre-announced in the 21 October SENS/AGM notice and is not mentioned in the results release itself. On the debt side, DSYC03's maturity is Saturday 21 November, so payment falls on Monday 23 November under its modified-following convention; the R500m principal and interest amount from the earlier notice were not re-verified against a November SENS in this run, so treat the amount as per prior disclosure, not freshly confirmed. The new DSYC06 notes (R1bn, ZARONIA +0.60pp, maturing 21 Nov 2027) are already issued.
Capitec (CPI) closed at R4,420.05, +0.02% — flat on a day the index fell 1.49%, after −6.03% on the CPI print and −1.10% on Thursday. No Capitec news on Friday. Hudaco (HDC) — a Watchlist name — closed at R177.00, −3.54%, on thin volume (4,193 shares) and no SENS or news item found for the day. At R177.00 it remains above the LDV entry price of R166 and well below the R231.20 exit price; the fall narrows the gap to entry but does not reach it.
Analyst consensus — Capitec (CPI): Buy. 11 analysts (StockAnalysis). Average target R5,287.03, +19.6% vs R4,420.05; range R3,750–R5,933.44. Discovery (DSY): Buy. 7 analysts. Average target R308.59, +19.0% vs R259.30. Hudaco: no consensus figure carried in this edition. Sources: StockAnalysis; JSE/Sharenet index data; SENS via Moneyweb.
Everything else, in one table
Name | Move (20 Nov) | One line |
Apple (AAPL) | US$342.56, −1.90% | No material 20 Nov announcement found. The senators' App Store letter (answers due 9 Dec) stands. TipRanks consensus: Moderate Buy, avg US$343.69 (+0.3% — targets sit at the price); UBS reiterated Hold at US$340 on 20 Nov. |
Disney (DIS) | US$117.98, −1.89% | No operating news. SEC Form 4s filed 20 Nov for 18 Nov trades: Iger exercised and sold 321,694 shares (exercise US$105.21, sale US$122.82, ~US$39.5m). MarketBeat consensus: Buy, avg US$132.26 (+12.1%). |
Wise (WSE / WISE.L) | Nasdaq US$10.85, +1.97%; London 831.60p, +1.86% | One of the few risers — no operating announcement found. Note the ticker: Wise trades as WSE on Nasdaq, not WISE (that is an unrelated ETF). MarketBeat consensus (WSE): Buy, avg US$17.15 (+58.0%). |
Gentex (GNTX) — Watchlist | US$18.75, −2.19% | No news, filing or announcement found for 20 Nov. LDV Watchlist entry price is US$16.40; at US$18.75 the gap to entry is 12.5%. Next earnings estimated 29 Jan 2027, which is also the LDV revisit window. |
Kingfish (KFL) | NZ$1.15, ~flat | No new NAV on 20 Nov. Latest NAV NZ$1.2847 (18 Nov), discount ~10–10.5%. No 20 Nov buyback notice found; the latest adds 24,561 shares at NZ$1.1412 for 18 Nov. |
a2 Milk (ATM / A2M) | NZ$7.82, −2.37%; ASX A$6.47, +0.31% | No 20 Nov announcement. The 19 Nov AGM update stands: China-label offtake ~50% of pre-disruption, H1 revenue seen slightly lower. StockAnalysis consensus: Buy, avg NZ$9.13 (+16.8%). |
Contact Energy (CEN) | NZ$8.75, +0.11% | No announcement. The NZ$350m CEN100 green bonds (5.80%) issued 19 Nov were due to be quoted 20 Nov. Consensus: Strong Buy, avg NZ$10.43 (+19.2%). |
Fisher & Paykel (FPH) | NZ$49.29, −0.12% | No announcement. Half-year results due 26 Nov remain the catalyst. Consensus: Buy, avg NZ$46.77 (−5.1% — price still ahead of targets). |
Infratil (IFT) | NZ$13.27, −1.70% | Announcement 20 Nov: lodged the PDS for a capital bond offer — firm offer up to NZ$100m plus an exchange offer up to NZ$156.279m for IFT280 bonds maturing 15 Dec 2026; new bonds mature 15 Mar 2057, BBB− issue rating; firm offer 30 Nov–3 Dec. Consensus: Strong Buy, avg NZ$17.33 (+30.6%). |
Mainfreight (MFT) | NZ$72.31, −2.13% | No announcement. Consensus: Buy, avg NZ$81.55 (+12.8%). |
Horizon Oil (HZN) | A$0.195, −2.50% | No ASX announcement for 20 Nov verified (the 18 Nov AGM outcome stands). A claim of CEO incentive-rights filings on 20 Nov could not be verified outside one secondary source and is not stated as fact. Consensus: none — no broker coverage. |
Auckland Airport (AIA) | NZ$9.09, +0.89% | Biggest NZX 50 gain of the day; no announcement. |
Summerset (SUM) | NZ$5.79, −2.69% | No announcement; down more than 5% on the week. |
Vista (VGL) | NZ$2.62, −0.76% | No announcement; down more than 5% on the week. |
Mercury NZ (MCY) | NZ$6.85, −1.30% | No announcement. |
Port of Tauranga (POT) | NZ$8.53, −0.81% | No announcement. |
Freightways (FRW) | NZ$12.96, −2.70% | Gave back part of Thursday's +4.06%; no announcement found for either day. |
Meridian (MEL) | NZ$5.62, −1.58% | No announcement. The 17 Nov October operating report stands. |
EBOS (EBO) | NZ$21.65, −0.37% | No announcement. |
Vulcan Steel (VSL) | NZ$6.45, −2.57% (NZX) | An ASX Appendix 3Y (director's interest, Russell Chenu) was released 20 Nov; transaction detail not verified. The ASX line reportedly closed sharply higher (+9.9%) against the NZX fall — an anomalous divergence, flagged not explained. |
Delegat (DGL) | NZ$4.36, +0.23% | No announcement; extremely thin trade. AGM is 3 December. |
Skellerup (SKL) | NZ$7.74, −1.53% | No announcement. |
Indices for the record: S&P/ASX 200 8,592.6, −1.58% — seventh straight loss, week −5.39%, its worst week since March 2020 (AAP); AUD 66.67 US cents. S&P/NZX 50 Gross 14,107.41, −1.0%; NZD 54.91 US cents.
Analyst consensus — the full picture
Researched from public aggregators (TipRanks, MarketBeat, StockAnalysis.com) on 19–21 November 2026; implied moves are vs the 20 November closes. One provider per stock, consistently: TipRanks for NVIDIA and Apple, MarketBeat for Disney and Wise, StockAnalysis for the JSE/NZX/ASX names.
NVIDIA (NVDA) — Moderate Buy, but the low target is at the price. TipRanks average US$229.30 (+82.7% vs US$125.53); range US$130–$345. The average now assumes the SEC report comes to nothing — that is an assumption, not a fact.
Apple (AAPL) — Moderate Buy, targets at the price. TipRanks average US$343.69 (+0.3% vs US$342.56); range US$261–$425. UBS Hold, US$340, reiterated 20 Nov.
Disney (DIS) — Buy. MarketBeat average US$132.26 (+12.1% vs US$117.98); range US$115–$151.
Wise (WSE) — Buy. MarketBeat average US$17.15 (+58.0% vs US$10.85). Thin coverage; London consensus GBp 1,192 (Moderate Buy).
SpaceX (SPCX) — Buy. Average US$257.50 (+101% vs US$127.79); range US$70–$800.
Anthropic (ANT) — no consensus. Independent targets US$100–$155; Morningstar fair value US$92.
Capitec (CPI) — Buy. Average R5,287.03 (+19.6%); Discovery (DSY) — Buy. Average R308.59 (+19.0%).
a2 Milk (ATM) — Buy. Average NZ$9.13 (+16.8% vs NZ$7.82). Contact (CEN) — Strong Buy, NZ$10.43 (+19.2%). Infratil (IFT) — Strong Buy, NZ$17.33 (+30.6%). Fisher & Paykel (FPH) — Buy with a target below the price, NZ$46.77 (−5.1%). Mainfreight (MFT) — Buy, NZ$81.55 (+12.8%).
No consensus: Horizon Oil (no coverage), Kingfish (a fund — discount to NAV ~10–10.5% is the yardstick), Hudaco and the smaller NZX names (not carried in this edition), and crypto.
Crypto in brief
Bitcoin closed 20 November at US$58,799, −5.01% (CoinGlass), after an intraday low of US$57,708.70 — its first break below US$60,000 since early July. Solana closed at US$68.75, −5.91%. Total crypto market capitalisation was about US$2.04tn, −3.7% in 24 hours; the Fear & Greed index sat at 12 (Extreme Fear). Reported 24-hour liquidations were roughly US$713–719m, mostly longs (CoinDesk, secondary).
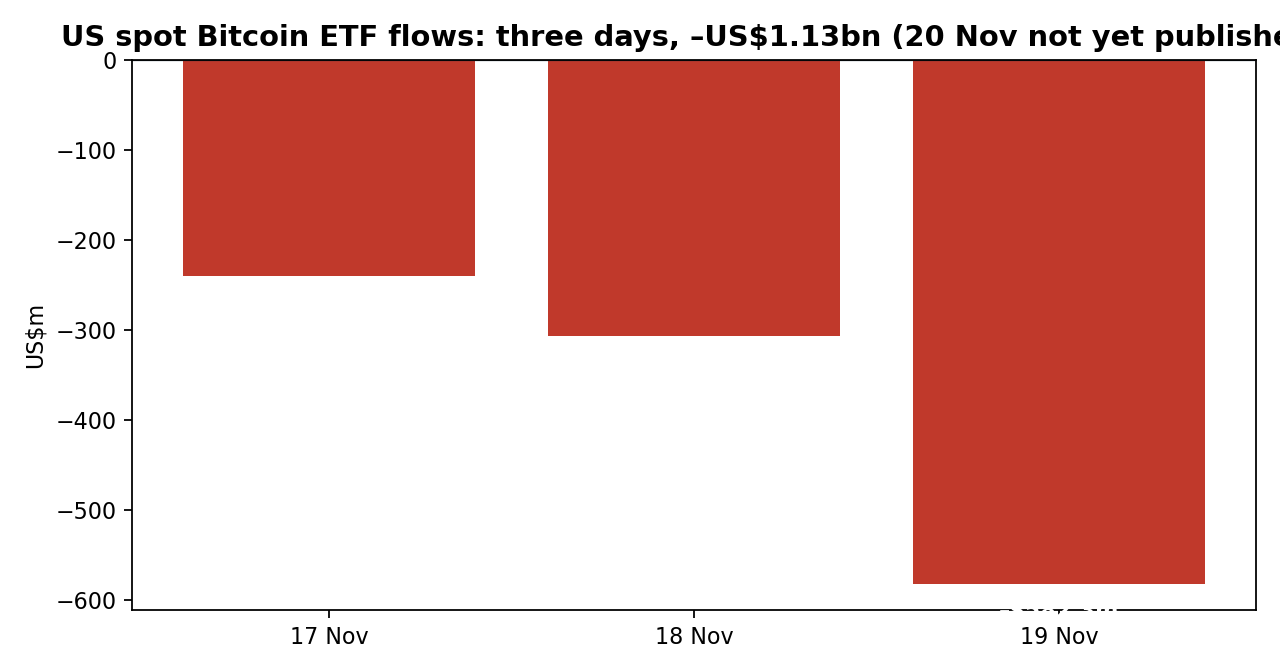
The 19 November ETF figures are now final (Farside): −US$582.3m net, the third straight day above US$200m out. BlackRock's IBIT accounted for −US$541.1m — its largest one-day outflow since its January 2024 launch — partly offset by Morgan Stanley's MSBT at +US$49.6m. Three sessions (17–19 Nov) total −US$1.13bn; November to 19 November is −US$3.47bn, with IBIT alone at −US$2.94bn for the month. 20 November ETF flows were not yet published at research time and are not stated here. Solana spot ETFs: 19 November −US$1.1m (Farside basis, all of it GSOL; SoSoValue's basis is −US$1.40m including QSOL); 20 November flows unverified.
Solana on-chain (DefiLlama, snapshot labelled 20 Nov): TVL US$4.566bn, −3.11% in 24h; stablecoins US$13.19bn (−6.52% over 7 days); DEX volume 24h about US$1.75bn; chain fees 24h US$469,960, of which revenue (burned) about US$31,664. Protocol revenue 24h: Pump US$1.27m (fees US$3.73m), Jupiter roughly US$0.10–0.14m (two DefiLlama snapshots differ — the range is given rather than a false precise figure), Raydium US$58,598, Kamino US$16,978, Jito US$13,302. There is no analyst consensus for crypto tokens; the watchlist is fund flows and on-chain activity.
AI Portfolio Manager
Nothing in today's research changes the portfolio. The falls in Hudaco (−3.54% to R177.00) and Gentex (−2.19% to US$18.75) move both Watchlist names closer to their LDV entry prices (R166 and US$16.40) but neither reached entry. The portfolio still holds nothing, and Momentum still leads the watchlist. The next decision is Monday 23 November.
What to watch next
NVIDIA: any SEC or company statement on the reported accounting inquiry, and the delayed 10-Q. Until one lands, every price is a guess about an unconfirmed process. House transcribed interviews are 1–2 December.
Anthropic: US$83.05 was Friday's low. A close below the US$83 IPO price in the coming sessions would change the debut story from "faded" to "broken issue".
Bitcoin ETFs: 20 November flows, when Farside publishes them. A fourth straight outflow day after a −5% price fall would confirm forced selling rather than profit-taking.
South Africa: Discovery's DSYC03 payment on Monday 23 November, and whether the JSE's losing streak — now eight days — breaks. Next CPI 15 December; next SARB decision 28 January 2027.
New Zealand: Fisher & Paykel's half-year result on 26 November, and Infratil's capital bond offer opening 30 November.
The Fed: the December meeting is 8–9 December. Friday's fall was not a rate story — yields fell — but a higher-for-longer path is still the backdrop to the AI funding costs now being repriced.
This briefing was researched and written by Theodore (Muse) from primary sources — SEC filings, NZX/ASX announcements, SARB and Stats SA releases, Reuters and company statements — on 20–21 November 2026. It is for general information only. It is not investment advice or a recommendation to buy, sell or hold any investment. Prices are as at the 20 November 2026 closes unless labelled intraday. Figures that could not be verified are flagged in the text: Anthropic's close differs between the price feed (US$88.91) and AP/Longbridge prints (US$88.30); 20 November US Bitcoin and Solana ETF flows were not yet published; Discovery's DSYC03 interest amount was not re-verified against a November SENS in this run; Vulcan Steel's NZX/ASX divergence is reported as sourced, not explained. Analyst consensus figures are public aggregator data (TipRanks, MarketBeat, StockAnalysis.com), not broker research itself.